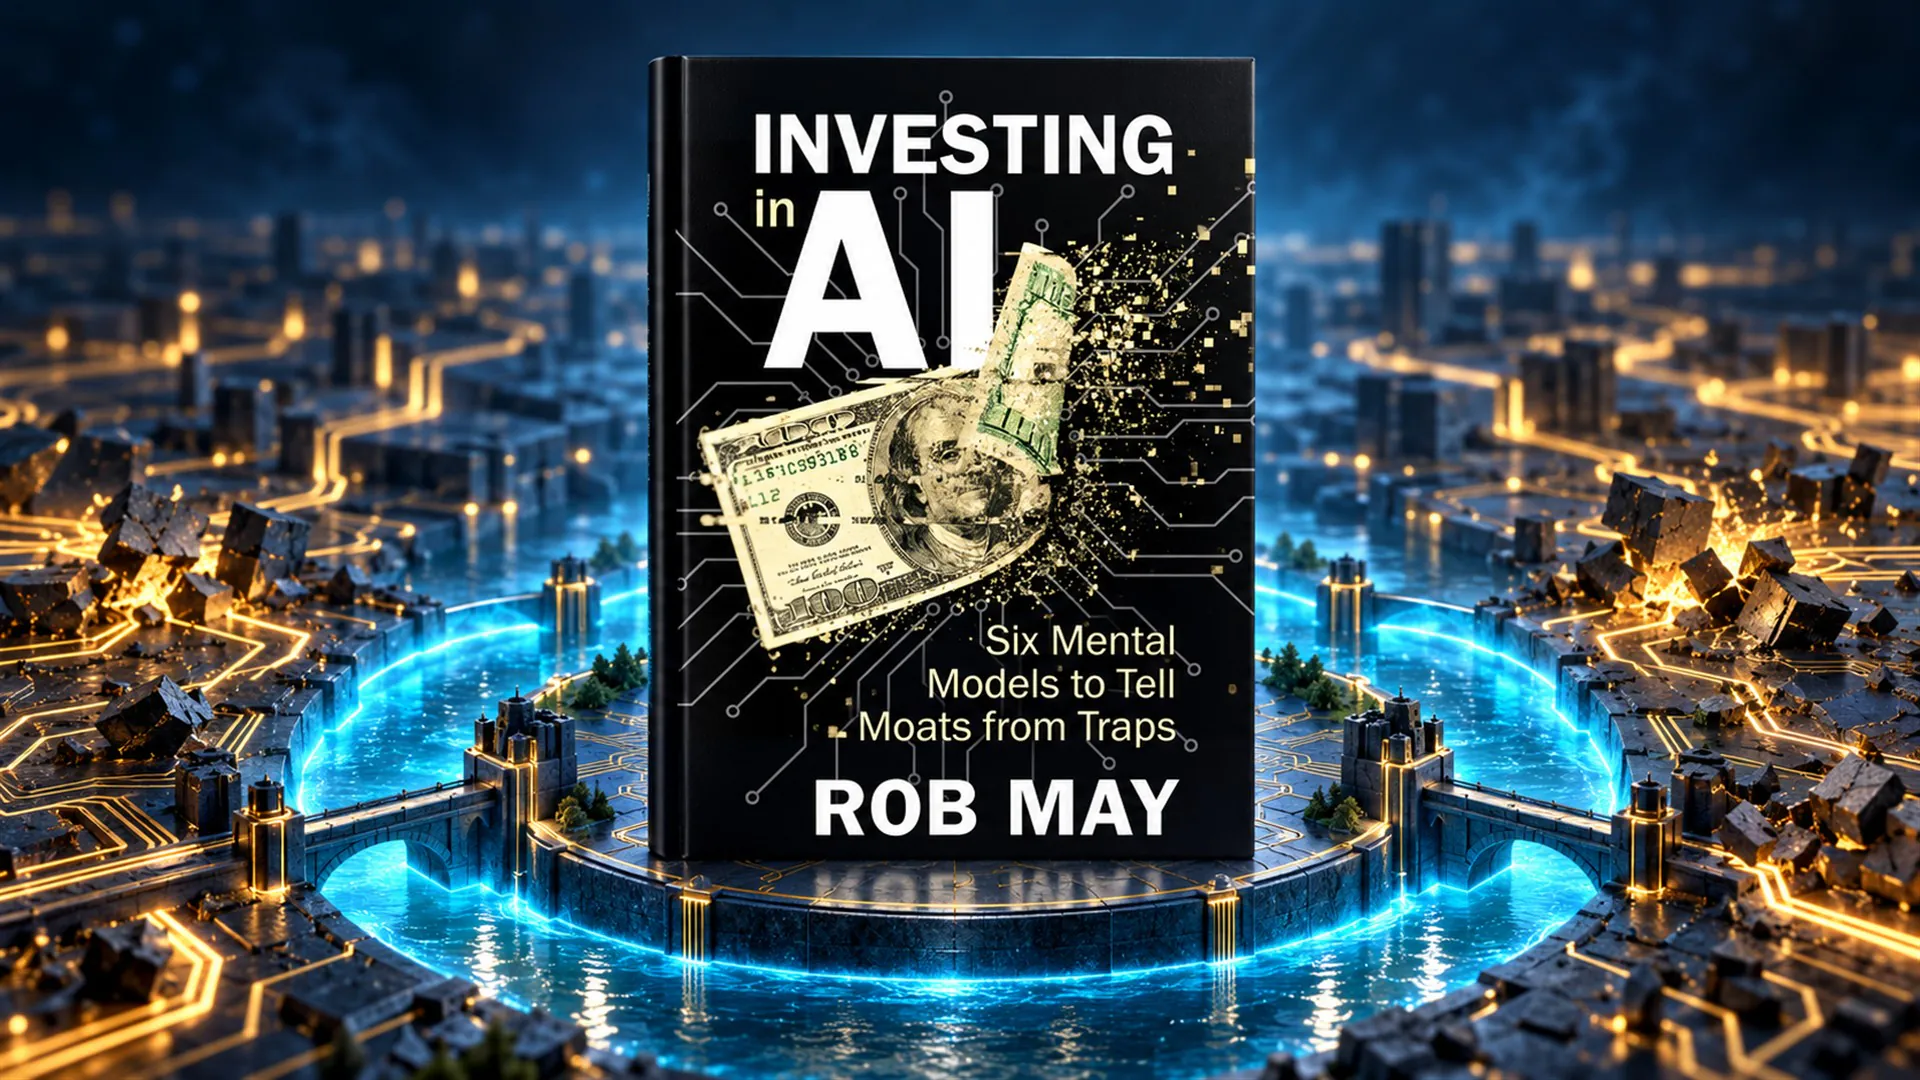
Book review: Investing in AI: Six mental models to distinguish ditches from traps by Rob May – Unite.AI
I was excited to read Investing in AI: Six Mental Models to Tell Moats from Traps, especially because I’ve been following Rob May for years through his Investing in AI newsletter. What sets Rob May apart from many investors, in my opinion, is his willingness to avoid groupthink and first-principles reasoning. Look beyond the prevailing narrative to ask how a company actually works, where its advantages come from, and whether those advantages can survive the next technological change.
This is where this book shines. It’s the first book I’ve come across that addresses investing in AI in this way. Rather than simply identifying an interesting technology or growing market, he asks readers to redesign how they analyze the companies building around it. The opportunity is huge, but recognizing a promising AI capability and recognizing a company to invest in are two very different skills.
When the AI narrative becomes reality
Rob May grounds the discussion in stories that will be familiar to anyone who has followed the AI ecosystem. Jasper became a media darling and raised $125 million at a $1.5 billion valuation. So ChatGPT brought powerful text generation directly to consumers, challenging the value of a product built around access to similar underlying functionality. Rob May uses inversion to examine how quickly an apparent advantage can become vulnerable.
What interests me about this example is the question it forces an investor or founder to grapple with: What does the customer still need from your company when the underlying technology becomes widely accessible? What differentiates a company with a defensible moat from a mere AI shell? A head start may buy time, but it doesn’t answer that question. Workflow ownership, distribution, specialized knowledge, and customer relationships all become much more important once access to the model becomes commoditized.
DeepSeek presents the other side of this uncertainty. The book discusses the shock resulting from the emergence of a GPT-4 class model with a reported training cost of $5.576 million. The investment lesson is significant: An assumption about the cost of competition can change much more quickly than a valuation model predicts.
Why You Need to Rethink Your SaaS Playbook
Rob May revisits AI winters of the past and argues that the scale of today’s deployment has broken the old pattern of promising demonstrations followed by widespread disappointment. His thesis is that useful AI is now embedded in too many real-world workflows to simply retreat to the lab. However, even with continued adoption, it can still be difficult to identify the next unicorn that can benefit from that adoption.
He identifies four key differences that help explain the change: AI can do cognitive work, learn from data, change the expectations of people who use it, and become a default part of the lives of a generation that grows up with it. The third point – reflexivity – is particularly interesting. Once customers experience a capability, they start to expect it elsewhere. The market served by a company changes as technology is adopted.
The biggest game changer is the speed of scaling. AI-related companies can reach substantial scale on timescales that were previously exceptional outliers. But evaluating them still requires understanding the business model. Charging by activity or by outcome creates a different relationship between value, revenue and costs than selling a fixed number of software seats.
Some SaaS lessons remain extremely relevant. Industry expertise is still important. Vertical-specific tools that understand an industry’s real problems can create significant benefits. Proprietary data loops can compound and deep integrations can create switching costs. The challenge is distinguishing these durable strengths from features a customer might get from dozens of other vendors.
Six mental models that improve questions
The book organizes its central argument around six mental models: understanding artificial intelligence as a set of technologies; challenge traditional assumptions of SaaS; expecting major market dislocations; recognize changes in markets and business strategy; understand faster scalability; and carefully evaluate the AI’s cost of goods sold.
They work well together because each exposes a different weakness in a superficial investment thesis. Calling a company an “AI business” says little about its economics. A dramatic increase in revenue says little about durability. A high gross margin today says little about what happens when customers start asking the product to do a harder job.
What I appreciate most is the habit of asking a second question. After asking if the technology works, ask yourself if it works reliably enough for the customer’s actual workflow. After asking if customers are paying, ask what they are paying and whether that spending is likely to continue. This makes the book useful beyond when its examples were written.
Botkeeper and the importance of cost trajectory
One of the most useful case studies is Botkeeper, an accounting automation company that Rob May invested in. He describes a company that initially relied heavily on human accountants and had gross margins of around 20-25%. This seemed unattractive to investors who expected margins from conventional software. But the work these people did also generated data that could help automate the process. Rob May reports that gross margins later topped 70% as more and more work shifted to software.
The lesson I take from all this is to examine what human engagement is building. If each completed task helps the system handle the next one more efficiently, the initial service costs could fund a more scalable task. If each new customer requires a proportional increase in permanent manual labor, the economics tell a different story.
Rob May also looks at the opposite trajectory: inference costs that become more challenging as usage grows. An AI system may require more calculations, repeated attempts, or human review to complete more difficult tasks. A product that seems attractive in a small pilot project can become expensive when customers rely on it for complex jobs. This is why cost direction matters just as much as current margin.
Efficiency is not automatically a moat
Another framework I have found useful is Rob May’s AI Value Triad: Commoditized AI, Core AI, and Expansion AI. In general, they describe capabilities that competitors can easily adopt, capabilities that strengthen a company’s existing advantage, and capabilities that open up new business opportunities.
His hypothetical airline example makes the first category easy to understand. An airline introduces an AI support agent and becomes more efficient. Competitors then adopt similar tools. What briefly seemed like a differentiator becomes an industry expectation, and some of the economic advantage may be negated by competition.
This is a useful antidote to viewing every AI announcement as evidence of a stronger business. I want to know what remains distinctive after competitors have access to comparable tools. A company that combines AI with proprietary feedback, deep operational knowledge, or a hard-to-replicate customer workflow has a more persuasive response than a company that advertises the same automation that everyone else can buy.
Look for operators who can put AI to work
The book is full of practical observations, including the importance of supporting operators who can effectively absorb AI. A concrete plan to change workflows and responsibilities is much more compelling than a pitch promising AI throughout the organization.
Rob May’s discussion of revenue quality reinforces this concept. Paid pilots and proofs of concept can generate impressive initial numbers, but should be separated from revenue related to ongoing production work. The useful question is: how much of the business would remain if customers stopped experimenting tomorrow?
I see this as especially valuable for founders. Winning a pilot is progress, but building a product that becomes part of how a customer does business is a different outcome. Understanding this distinction early can shape product priorities, hiring and how a company measures success.
Final verdict
My most important conclusion is that this book should not be reserved exclusively for investors. Entrepreneurs have just as much to gain by understanding what makes an AI company investable, how lasting advantages are formed, and what startup pitfalls can be avoided before they become costly.
It’s best approached as a framework rather than a list of stocks to buy. Its most important contribution is to help readers become more specific about why they believe in a company. Examples will inevitably age as the industry advances; the discipline of questioning assumptions is what gives the book its lasting usefulness.
Investing in AI: Six mental models for distinguishing ditches from traps provides the first-principles thinking that made me a reader of Rob May’s newsletter in the first place. For investors looking to separate a defensible business from a compelling story, and for entrepreneurs looking to build the former, this is a thoughtful and useful read.
Post Comment